They Took My Car After One Late Payment — Is That Even Legal?
You’re probably feeling shocked, angry, and confused. One missed payment, and your car’s gone? Believe it or not, in many cases, yes — it is legal. Let’s walk through how repossession works, why it happens, and what you can do next.

The Short Answer: Yes, They Usually Can
Most auto loan agreements allow the lender to repossess your car after any default — including just one missed payment. It’s harsh, but if it’s in the contract you signed, it’s enforceable in most states.
What “Default” Really Means
In the car loan world, “default” doesn’t always mean months of missed payments. It can be as simple as being late, not having insurance, or breaking another rule in your contract. It all depends on what you agreed to.
Your Contract Holds the Power
When you signed the loan paperwork, you agreed to specific terms. If the contract says the lender can repossess after one late payment, they legally can — even if you’ve never missed before.
Some States Require a Grace Period — Others Don’t
In a few states, lenders must wait or notify you before taking action. But in most, no warning is needed. Repossession can happen the day after you default, especially if you’ve been flagged as high risk.
No Advance Notice Required
This surprises a lot of people — but lenders don’t usually have to tell you before they repossess the car. They just need to do it “peacefully,” meaning no force, threats, or entering your locked garage without permission.
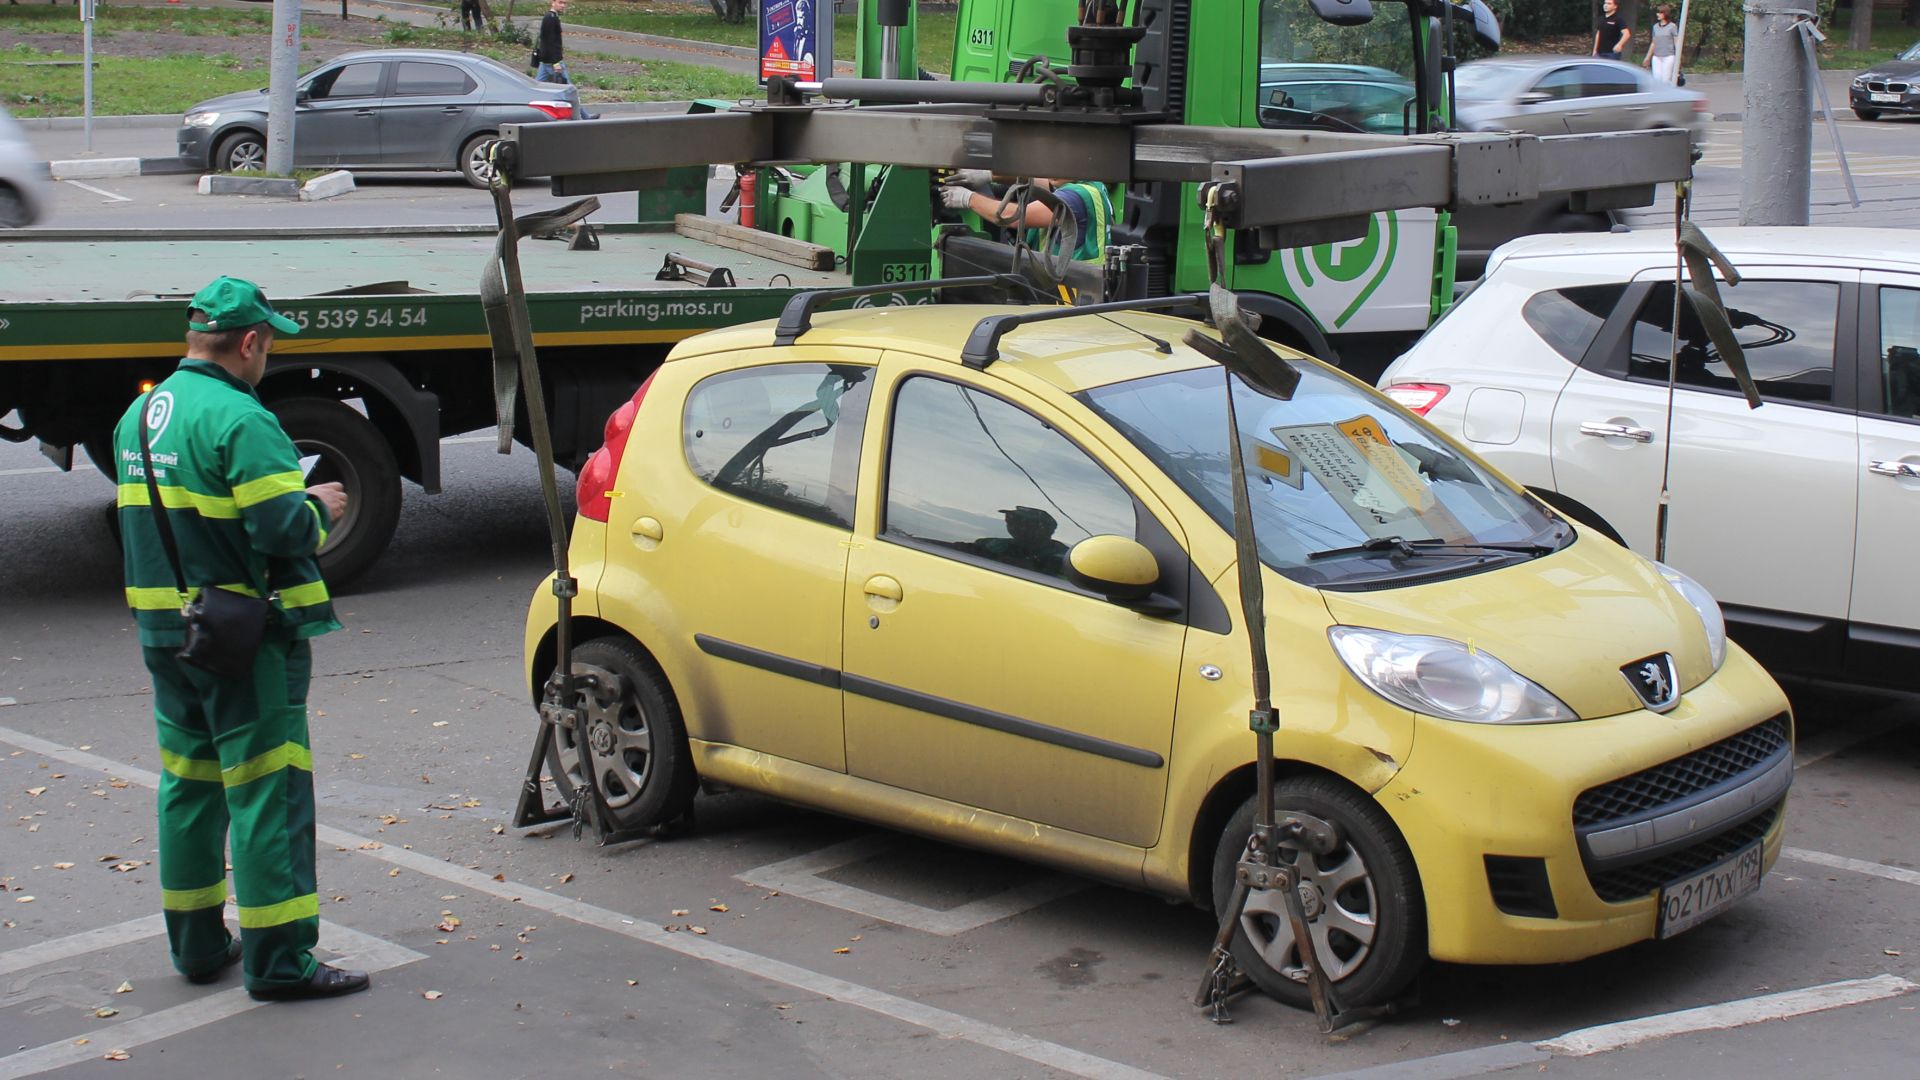
They Can Take It From Anywhere Public
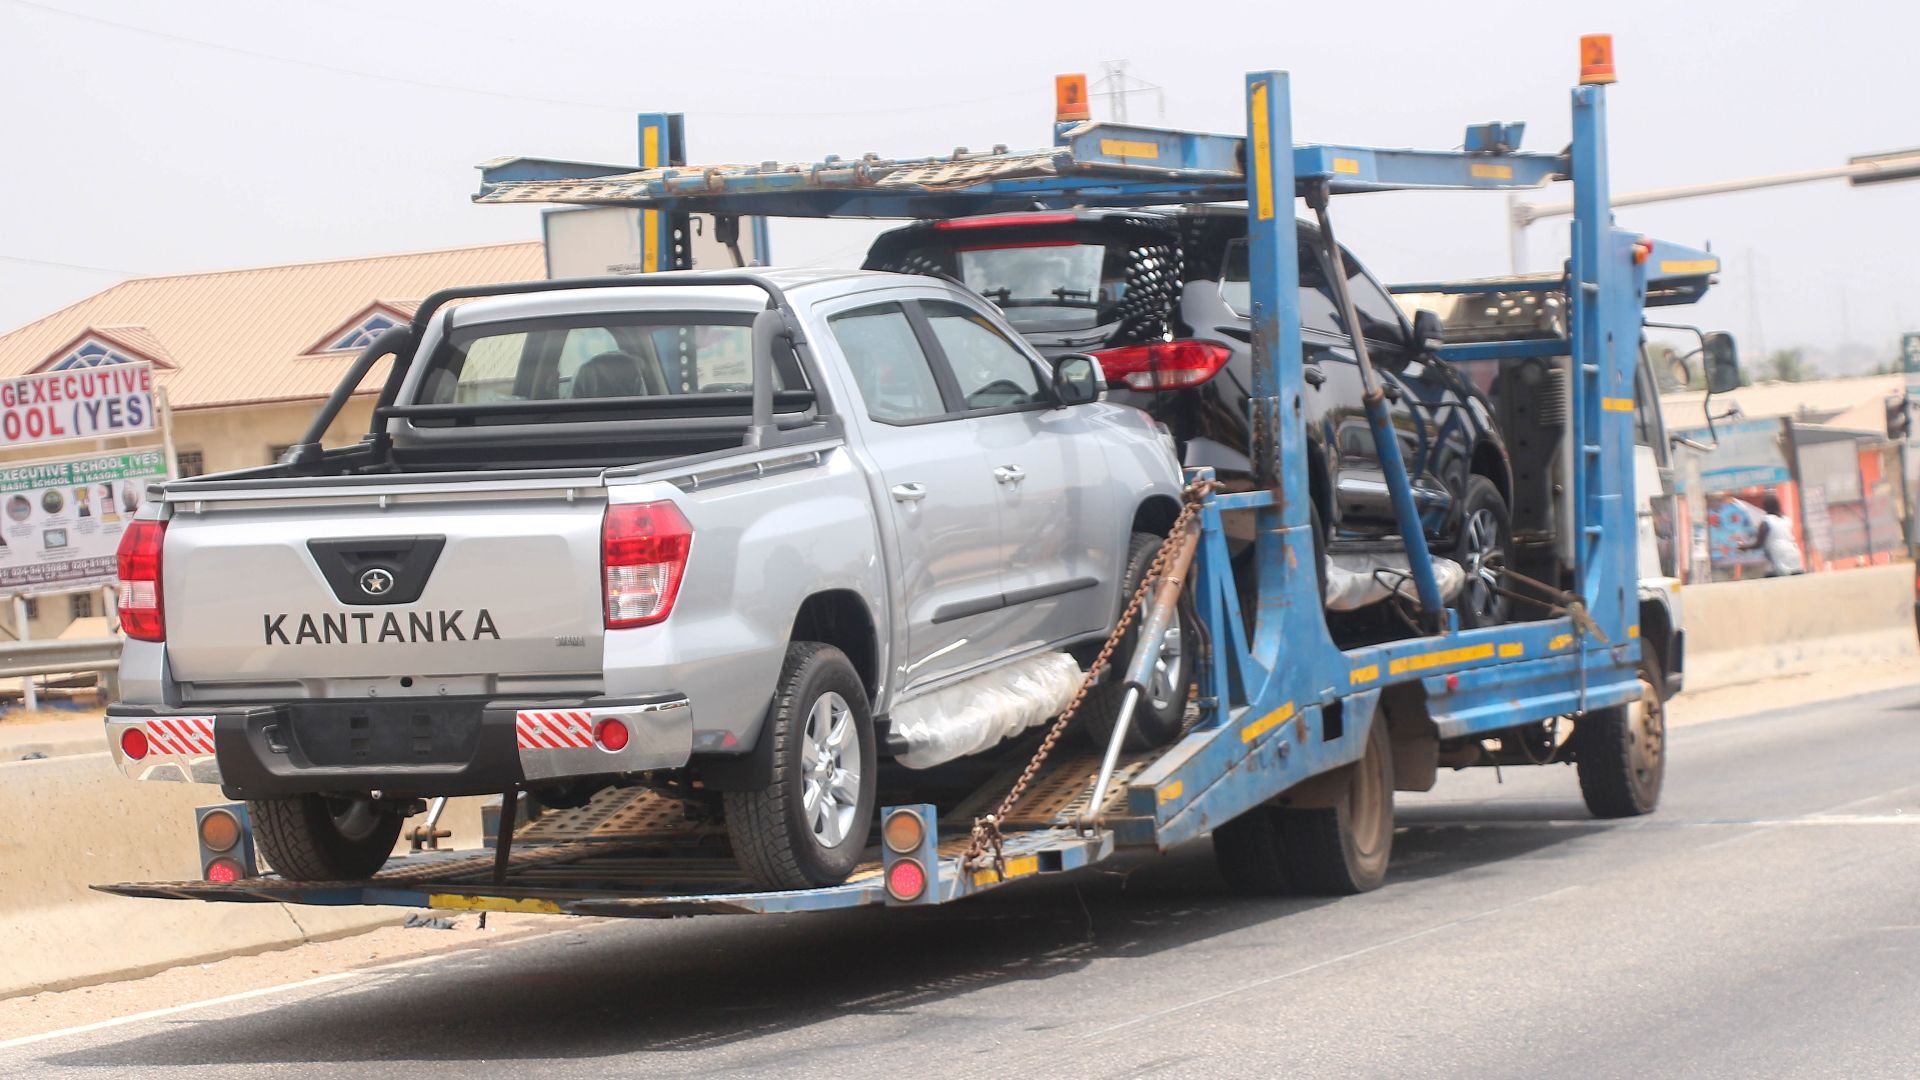
Repossession agents can legally tow your vehicle from your driveway, workplace, or even a store parking lot. If it’s out in the open and not locked in a garage, it’s fair game once you’re in default.
You May Still Owe Money
Getting your car repossessed doesn’t wipe out your loan. In fact, you’ll likely still owe the remaining balance — plus repossession fees, storage costs, and even legal fees if they resell the car for less than you owe.
It Damages Your Credit Big-Time
Repossession stays on your credit report for up to 7 years. It can tank your credit score, make it harder to get approved for future loans, and raise your interest rates when you do.
One Miss Can Still Trigger Repossession
Even if you’ve paid on time for years, a single late payment can put you in default. Some lenders are stricter than others, especially if the loan was already considered high-risk or subprime.
Why Some Lenders Move Fast
If the lender thinks you’re about to stop paying entirely, they may act quickly. Repossessing early reduces their financial risk — especially if your vehicle is losing value fast or your loan is already upside down.
They Might Not Repossess Right Away
Just because they can doesn’t mean they will. Some lenders allow a short grace period or try to contact you first. But if you’re unresponsive or have a history of missed payments, they may act fast.
Can You Get the Car Back?
Yes — but act fast. You might be able to reinstate the loan by paying what you owe, including fees. Some states give you a redemption period, usually a few days to a few weeks, to catch up before it’s sold.
Reinstatement vs. Redemption
Reinstating means catching up on missed payments and fees to keep your loan going. Redemption means paying the entire loan balance plus fees to get the car back. Either way, you’ll need cash — and quickly.
What If You Were Just a Few Days Late?
Even being a few days behind can technically trigger repossession. That’s why it’s so important to call your lender and communicate. Many will work with you if you explain the situation — before the tow truck arrives.

They Can’t Breach the Peace
Repossession agents can’t threaten you, physically remove you from the car, or break into a locked garage. If they do, you may have legal grounds to challenge the repossession and even sue.
Know Your Rights
Each state has different repossession laws. Some require written notices, some limit fees, and some protect you from immediate repossession. Check your state’s consumer protection agency for specifics on your rights.
What You Should Do Right Away
Call your lender. Ask what you owe and if you can reinstate or redeem the loan. Also ask where your vehicle is being held and what the timeline is before it’s auctioned. Time is critical here.

Don’t Ignore the Debt
Even if the car is gone, the loan isn’t. You’re still on the hook for the balance — and any legal fees if they sue you to collect. Try to negotiate a payment plan, or consult a credit counselor.
Can You Fight It?
If the lender broke the law or didn’t follow your state’s rules, you might be able to challenge the repossession. Talk to a consumer protection attorney if something feels off, especially if you were never late.
It Feels Harsh — Because It Is
Repossession is one of the toughest financial consequences out there — especially after just one mistake. It feels unfair, and in many ways, it is. But legally, most lenders have the right. That’s why reading the fine print — and staying in touch — is so important.
You May Also Like:
My hybrid battery is dying and costs thousands to replace. Should I just buy a new car?
Ranking Toyota's Top Performers, According to J.D. Power