The Discount Comes With A Catch
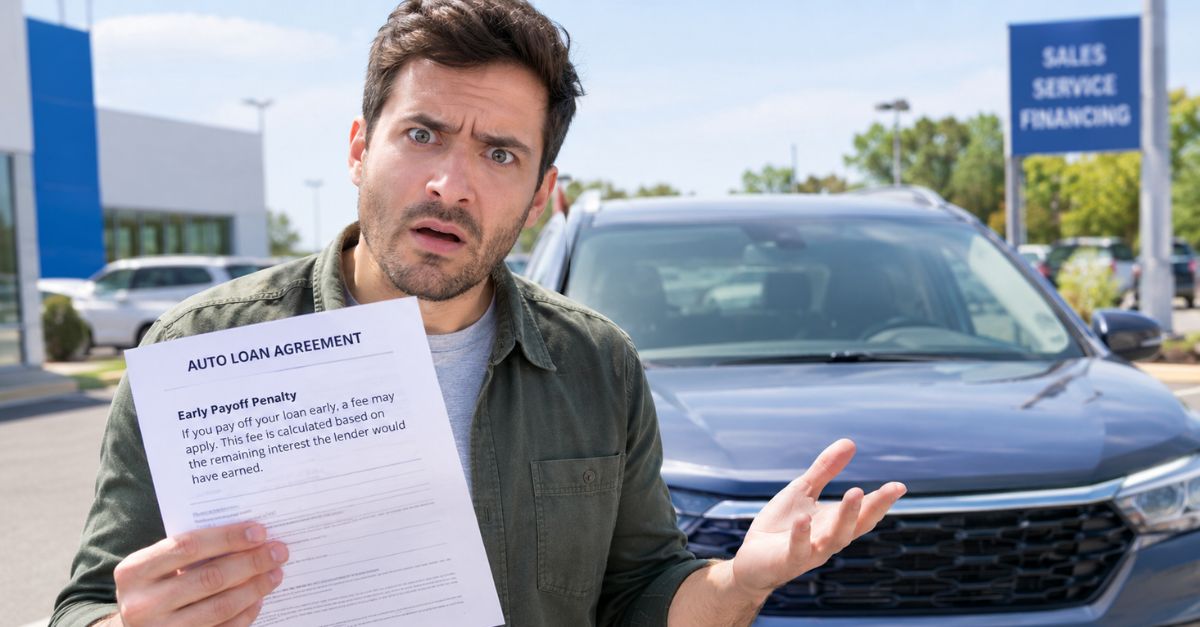
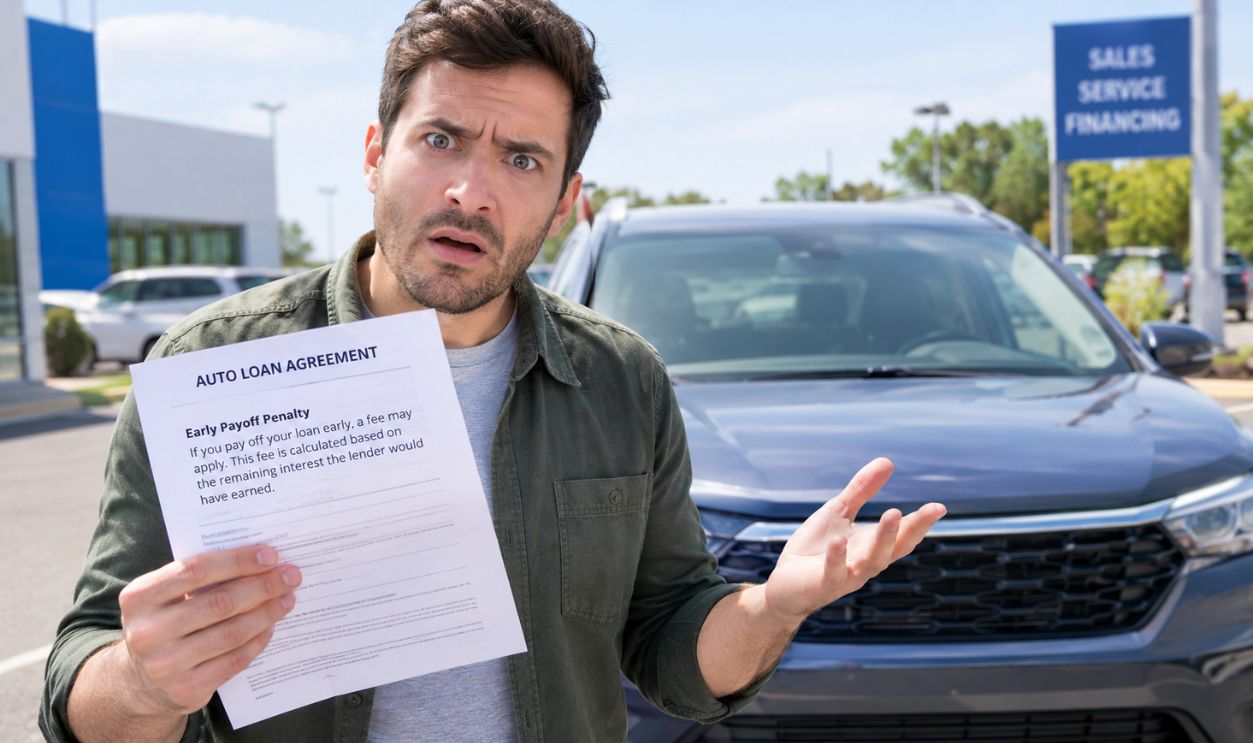
You see a big dealer discount, agree to finance the car, and then hear the warning that changes everything: pay off the loan too soon and the deal could disappear. It sounds shady, but sometimes there is a real reason behind it. The details are what matter.
Why This Question Keeps Coming Up
Buyers have been running into this for years because car financing is not just about borrowing money. It is also a major profit source for dealers and lenders. When a discount is tied to financing, the money behind the deal may work very differently than most shoppers think.
What Dealers Usually Mean
In many cases, the dealer is talking about a lender incentive or a dealer reserve payment. That money may only stick if the loan stays open for a minimum amount of time, often around 90 days, though the exact terms vary. If the buyer pays off the loan before that window closes, the dealer may have to give back some of what it earned.
The 90 Day Rule You Keep Hearing About
That 90-day guideline gets talked about a lot in the auto business, but it is not some universal law. It usually comes from agreements between lenders and dealers, not from a state rule that says buyers have to wait. What really controls the situation is the loan contract and the rebate or discount terms, not whatever gets said in the showroom.
What The CFPB Found About Auto Lending Incentives
On March 30, 2023, the Consumer Financial Protection Bureau published research explaining that many auto dealers get paid through finance markups. The CFPB said lenders often set a buy rate, then allow dealers to raise the rate offered to the buyer, with the dealer keeping part of the difference. That matters because it shows why dealers may push certain financing deals so hard.
Dealer Markups Are Real Money
The CFPB also said in that 2023 analysis that discretionary dealer markups can raise a buyer's costs without improving the loan at all. That helps explain why some financing discounts look great upfront but are tied to backend profit. The discount may be real, but the dealer may still expect to make money once the financing kicks in.
Why Early Payoff Can Sting The Dealer
If a lender pays the dealer a commission for setting up the loan, that money may be subject to a chargeback. In simple terms, the lender can take back some or all of the dealer's payout if the loan ends too quickly. That is often the real reason behind the warning not to pay the loan off early.
What The FTC Says About Add Ons And Financing
On December 12, 2023, the Federal Trade Commission announced action against Passport Automotive Group and described deceptive practices tied to pricing and add-ons. The FTC said advertised discounts were not always available the way they were presented and that buyers could get hit with surprise charges. The case was not just about early payoff, but it showed how discounts and financing can be bundled together in ways that deserve a close look.
Discounts Can Be Conditional
A dealer discount might be unconditional, or it might depend on something specific, like using the dealer's preferred financing partner. Sometimes that condition is stated clearly in the buyer's order or rebate form. Sometimes it is buried in the paperwork or mentioned vaguely at the desk, which is where trouble starts.
 f.t.Photographer, Shutterstock
A Rebate Is Not The Same As A Dealer Promise
Manufacturer rebates and dealer discounts are not the same thing. A factory rebate usually comes with formal rules, published eligibility requirements, and set program dates. A dealer-funded discount may be more flexible, but that also means the store may attach its own conditions, subject to contract law and consumer protection rules.
If It Is In The Contract, Read The Exact Words
The quickest way to cut through the confusion is to read the retail installment sales contract and every rebate or discount form. Look for language about chargebacks, minimum finance periods, rescinded discounts, or financing conditions. If the payoff warning is real, the safest place to prove it is on paper.
Federal Law Gives You A Key Protection
The Truth in Lending Act gives borrowers an important basic protection on many consumer loans. According to the CFPB's explanation of auto loans, lenders generally cannot charge a prepayment penalty on a car loan. That means paying off the loan early usually should not trigger a direct lender fee, though a separate discount condition can still be a different matter.
No Prepayment Penalty Does Not End The Story
This is the part that confuses people. A loan can have no prepayment penalty, yet a related dealer discount can still come with conditions tied to financing. Put simply, the lender may not charge you for paying early, but the dealer may say the discount depended on keeping the loan open for a certain amount of time.
State Attorneys General Have Warned Buyers To Read Closely
Consumer advisories from state officials often tell buyers to check whether rebates or special pricing require dealer-arranged financing. For example, the North Carolina Department of Justice warns buyers to read all financing terms carefully and understand the total cost before signing. It sounds routine, but it can save you a lot of money.
Can A Dealer Force You To Keep The Loan For Months
Usually, a dealer cannot just make up a post-sale obligation that is not in the documents you signed. If there is no written term saying you lose the discount after an early payoff, the dealer may not have much of a case. Sales staff can say a lot in the finance office, but enforceable terms usually need to be in the paperwork.
What If The Dealer Threatens To Bill You Later
If the dealer says it will send you a bill after you pay off the loan, ask for the exact signed document that allows it. Ask for the date, the form name, and the specific clause. If they cannot point to that, the threat may be more pressure tactic than legal right.
Spot Delivery Can Complicate Things
Another twist is spot delivery, sometimes called yo-yo financing, where you take the car home before financing is fully final. The FTC and state regulators have repeatedly warned about dealers changing terms after the fact in some of these deals. If your financing was never fully locked in, a fight over the discount can get messier fast.
Why Dealers Push Financing Even On Cash Buyers
Sometimes a dealer offers a better out-the-door price only if you finance through its lender network. That is because the sticker price is only one part of the deal. The dealer may be willing to give up some profit on the car if it expects to make money on financing, products, or lender compensation.
The Smart Buyer Workaround
If the loan terms allow it and the discount is worth it, some buyers take the financing, make a few payments, and then pay off the loan after the period the dealer mentioned. The catch is obvious: only do that if the paperwork supports the timing and the loan truly has no prepayment penalty. Never rely on a wink and a nod when a contract is involved.
Ask These Questions Before You Sign
Ask whether the discount is coming from the manufacturer, the dealer, or the lender. Ask whether there is any written minimum finance period and whether paying off early changes the sale price. Then ask for copies of every document that mentions the rebate or discount before you agree to anything.
Check The APR, Not Just The Monthly Payment
A tempting financing discount can stop looking so good if the interest rate is inflated. The CFPB has repeatedly warned that focusing only on the monthly payment can hide the real cost of credit. A small discount upfront can get wiped out by a higher APR, even over a short stretch.
Look For Add Ons Hiding In The Deal
Gap coverage, service contracts, theft products, and other extras can get folded into the financing with very little discussion. FTC enforcement actions have shown how these products can raise the amount financed and blur what first looked like a clean discount. If the dealer wants you to finance, check the extras even more carefully.
 https://kaboompics.com/, Pexels
What To Do If You Already Signed
Gather your retail installment contract, buyer's order, rebate forms, and any emails or texts that mention the discount. Then call the lender and confirm whether the loan itself has any prepayment penalty and whether the dealer's financing incentive is separate. After that, compare the dealer's warning with the actual written terms.
When To Push Back Hard
If the dealer cannot point to a signed clause and still tries to claw back the discount, it may be time to escalate. You can file complaints with your state attorney general, your state motor vehicle agency, the FTC, or the CFPB, depending on the problem. Keep screenshots, voicemails, and signed forms because written records matter.
The Bottom Line On Early Payoff
Can a financing deal really penalize you for paying off a car loan faster? Sometimes yes, but usually only if the discount was clearly tied to keeping the loan for a certain period. The lender generally cannot spring a prepayment penalty on a standard car loan, but a dealer discount can come with strings if those strings were properly disclosed and agreed to.
The Best Way To Protect Yourself
Get every promise in writing before you drive away. If a dealer says you must keep the loan for 90 days, ask them to show you exactly where that appears in the signed paperwork and what happens if you do not. A good deal can still be a good deal, but only if the fine print matches the sales pitch.