That Expensive Lesson Just Got Even More Expensive
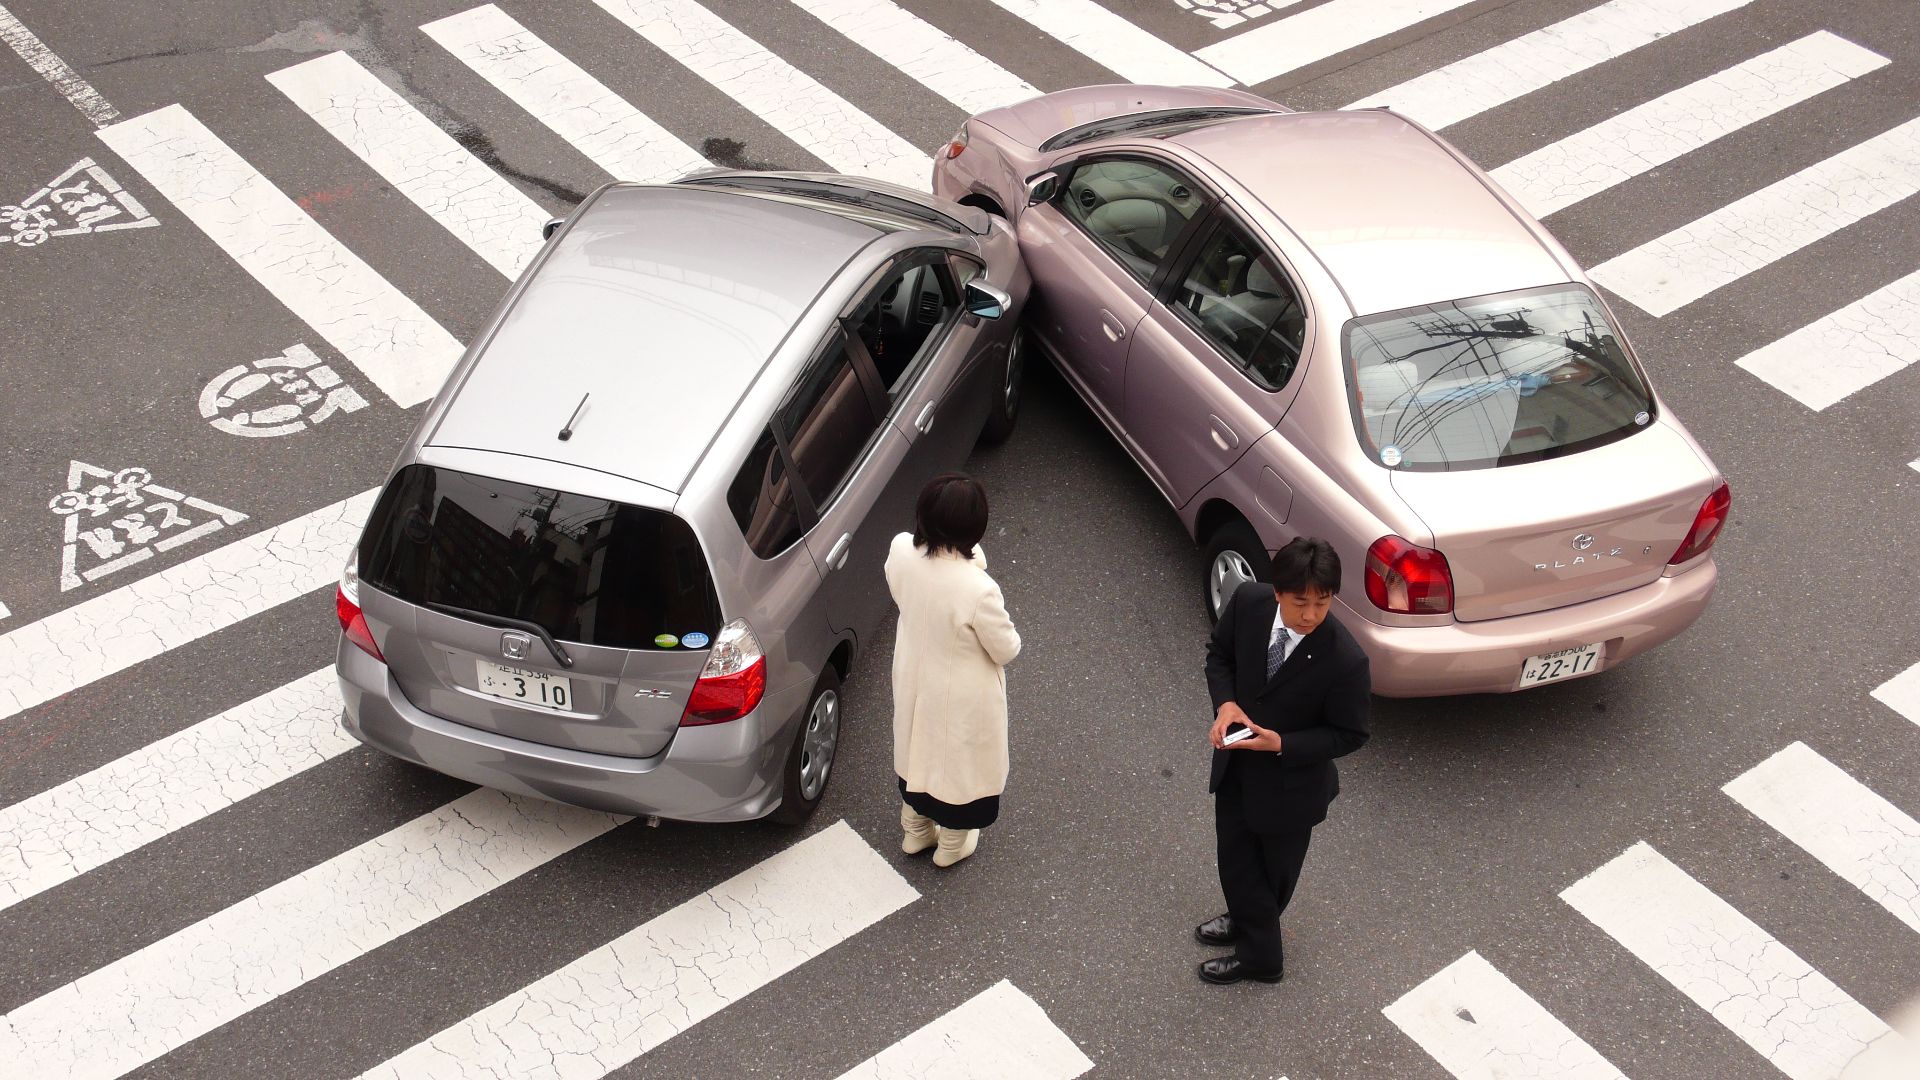
Your child crashes your car, the insurance claim gets filed, and then the renewal notice shows up looking absolutely unhinged. Suddenly your premiums have doubled, and now you’re wondering why you’re being punished when you’re not even letting them touch the keys anymore. If their no longer driving the car, shouldn’t the insurance company back off? The frustrating reality is that insurers often look at what already happened, not just what you promise won’t happen again. But that doesn’t necessarily mean you’re stuck paying sky-high rates forever.

Insurance Companies Care About Risk History
This is the part that catches a lot of people off guard. Insurance pricing is heavily based on past claims and driving history. Once an accident happens, especially one involving a driver connected to your household or policy, the insurer sees increased risk. Even if your child never drives your car again, the accident itself is now part of the insurance record.
Why Your Premium Went Up So Much
A major accident claim can trigger significant premium increases, especially if your insurer paid out a large amount for vehicle damage, injuries, or liability claims. From the insurance company’s perspective, they just experienced a costly loss connected to your policy. That often leads to higher rates at renewal.

Household Drivers Matter More Than People Realize
Insurance companies don’t just insure the car, they insure the overall risk associated with the household and drivers who may reasonably have access to it. If your child lives with you or previously had regular access to the vehicle, insurers may still factor them into the risk calculation even if you say he won’t drive anymore.

“Occasional Drivers” Still Count
Even if your child wasn’t officially listed as the primary driver, insurers may still view them as an occasional driver if he used the car regularly. That’s one reason claims involving family members often impact premiums so heavily.

Removing Them From The Policy Can Help
The good news is that if your child truly will no longer drive the vehicle, removing them from the insurance policy may reduce future premiums. It won’t erase the accident history, but it can help limit the insurer’s ongoing perception of risk.
Some Companies Require Driver Exclusions
In some states, insurers allow something called a named driver exclusion. This means you formally agree that your child will not drive the vehicle under any circumstances, and the insurer excludes them from coverage. That can sometimes lower premiums significantly. But there’s a huge catch: if he drives the car anyway and crashes again, the insurer may deny coverage completely.

Accident Surcharges Usually Don’t Last Forever
One important thing to remember is that accident-related premium increases are typically temporary. Depending on the insurer and state, accidents often affect rates for around three to five years. That’s not exactly comforting right now, but it does mean this isn’t necessarily permanent.

Your Child ‘s Age Probably Didn’t Help
If your child is a younger driver, the premium jump may have been even worse. Younger drivers are already considered higher risk statistically, so a crash involving them can hit premiums especially hard.

Fault Matters Too
Whether your child was considered at fault in the accident makes a huge difference. At-fault accidents usually trigger much larger rate increases than not-at-fault claims.
 Shuets Udono, Wikimedia Commons
Step One: Ask Your Insurer Exactly Why The Rate Increased
Before assuming the worst, call your insurer and ask for a breakdown of the premium increase. How much is tied to the accident itself? How much relates to your child being listed as a driver? Understanding the details helps you figure out your next move.

Step Two: Ask About Removing Your Child From The Policy
If they truly won’t be driving the vehicle anymore, ask what happens if you remove them from the policy entirely. Some insurers may adjust the premium immediately, while others may still factor in the recent claim history for a while.

Step Three: Ask About Driver Exclusion Options
If your state allows named driver exclusions, ask whether that’s available. Again, this only works if you are absolutely certain he will not drive the vehicle again because coverage could disappear if he does.

Shopping Around Can Make A Huge Difference
Here’s something many people don’t realize: different insurers react very differently to accidents. One company might double your premium while another increases it far less. Shopping around after a claim can sometimes save thousands.

Loyalty Doesn’t Always Pay Off
A lot of people assume staying with the same insurer guarantees the best treatment after an accident. Unfortunately, that’s not always true. Sometimes long-time customers get hit with major increases anyway, which is why comparing quotes is so important.

Defensive Driving Discounts May Help
Depending on your insurer and state, completing a defensive driving course may help reduce premiums slightly. It won’t erase the accident, but every little bit can help when rates spike dramatically.

Raising Your Deductible Is Another Option
If your premium feels completely unmanageable, increasing your deductible may lower the monthly cost. Of course, that means paying more out of pocket if another accident happens, so it’s a trade-off.
Unfortunately, The Insurer Doesn’t Just Take Your Word For It
This is the hard truth. From the insurer’s perspective, saying “he won’t drive anymore” doesn’t fully erase the risk because access to the vehicle still exists unless formal policy changes are made. That’s why simply making a promise usually isn’t enough on its own.
But This Situation Is Usually Fixable Over Time
The encouraging thing is that premium spikes after accidents often improve gradually, especially if you maintain a clean driving record going forward and your child is removed from the policy. This may feel brutal right now, but it’s not necessarily your forever insurance rate.
Final Thoughts
It feels unfair when your insurance rates explode after your child crashes your car, especially if you’re no longer letting them drive it. But insurance companies price policies based heavily on past claims and household risk, not just future promises. The good news is that you’re usually not trapped permanently. Between policy changes, shopping around, and time passing, there are often ways to gradually bring those premiums back under control.
You May Also Like: