Concerned woman with young man in car behind her.

I let my adult son borrow my car from time to time, and now my insurance premium has skyrocketed. Do I really have to disclose that?


June 3, 2026 | Allison Robertson

I let my adult son borrow my car from time to time, and now my insurance premium has skyrocketed. Do I really have to disclose that?


Letting Him Borrow the Car—Now Your Insurance Bill Exploded? 

You let your adult son borrow your car every now and then—no big deal, right? Then your renewal hits, and suddenly your premium has jumped way up. Now you’re wondering… did you actually do something wrong by not mentioning it?
Concerned woman with young man in car behind her.

Advertisement

Why This Situation Catches People Off Guard 

A lot of people assume occasional borrowing doesn’t matter. It’s your car, your policy—so why would it affect anything? But insurance companies see things very differently.
A classic green car being driven outdoors on a sunny day with a blurred background.Helena Jankovičová Kováčová, Pexels

Advertisement

How Insurance Companies View Drivers 

Insurance isn’t just about the car—it’s about who drives it. The more drivers, and the riskier those drivers are, the higher the potential for claims.
Smiling African American man in a car, enjoying a drive. Captured in a relaxed and candid moment.cottonbro studio, Pexels

Advertisement

The Key Term—“Household Drivers” 

Most policies require you to list anyone in your household who has regular access to your vehicle. That includes adult children—even if they don’t own the car.
Businessman signing important documents at office desk.Kampus Production, Pexels

Advertisement

What Counts as “Regular Use”? 

This is where things get tricky. Occasional borrowing might be fine—but if your son uses the car frequently or has easy access to it, insurers may consider him a regular driver.
man driving straight on pathway during day timeAlex Jumper, Unsplash

Advertisement

Why Age and Driving History Matter So Much 

Younger drivers—especially those under 25—are statistically higher risk. Even a clean driving record can still lead to higher premiums simply based on age.
man in white crew neck t-shirt standing beside white car during daytimeValerie Kaarna, Unsplash

Advertisement

What Happens If You Don’t Disclose 

If the insurance company finds out later—especially after a claim—they may adjust your premium, deny coverage, or even cancel your policy.
Young woman with curly hair making an urgent phone call indoors, looking concerned.MART PRODUCTION, Pexels

Advertisement

How Do They Find Out? 

Claims investigations, accident reports, or even routine policy reviews can reveal undisclosed drivers. It’s not as hidden as people think.
Police officers handling a traffic violation in a parking lot, focus on policewoman writing a ticket.Kindel Media, Pexels

Advertisement

The “Permissive Use” Rule 

Most policies allow occasional borrowing by someone not listed—this is called permissive use. But it’s meant for rare situations, not ongoing access.
white BMW car on streetJon Koop, Unsplash

Advertisement

Where People Accidentally Cross the Line 

Letting your son borrow the car once in a while? Usually fine. Letting him use it every weekend or commute with it? That starts looking like regular use.
man in white crew neck t-shirt driving carUlrik Skare, Unsplash

Advertisement

Why Your Premium Suddenly Increased 

If your insurer discovered your son was driving more than expected—or added him to your policy—they recalculated your risk. That’s where the jump comes from.
A man in a suit happily drives a silver car through city streets on a rainy day.Alexander Mass, Pexels

Advertisement

Could They Add Him Without Asking You? 

In some cases, yes. If they believe someone in your household should be listed, they can add them—or require you to exclude them formally.
Senior man with eyeglasses sitting indoors, having a phone call. Calm and thoughtful atmosphere.SHVETS production, Pexels

Advertisement

What an “Excluded Driver” Means 

You can sometimes choose to exclude your son from the policy—but that means if he drives the car and gets into an accident, there’s no coverage at all.
man in black jacket wearing black sunglassesalexey turenkov, Unsplash

Advertisement

Why Insurance Companies Are So Strict 

Because undisclosed drivers are one of the biggest risks insurers face. More drivers = more exposure = more potential payouts.
Bearded man enjoying a drive through lush green countryside on a sunny day.Atlantic Ambience, Pexels

Advertisement

Is This Actually a Legal Requirement? 

It’s not usually a criminal issue—but it is a contract issue. Your insurance policy is a legal agreement, and failing to disclose drivers can violate its terms.
Two men discussing paperwork in a rustic office with exposed brick walls.Henri Mathieu-Saint-Laurent, Pexels

Advertisement

Can They Raise Your Rates Retroactively? 

They typically won’t charge you for the past—but they can increase your premium going forward once they identify the added risk.
A diverse group of employees working together in a bright, modern call center with headsets.Yan Krukau, Pexels

Advertisement

Can You Push Back on the Increase? 

You can ask for clarification, shop around for other insurers, or adjust your policy—but if your son qualifies as a regular driver, the increase is usually justified.
Young Asian female in casual clothes standing near window and answering phone call in cozy room at homeJESSICA TICOZZELLI, Pexels

Advertisement

So… Do You Really Have to Disclose This? 

In most cases, yes. 

If your adult son lives with you or regularly uses your car, you are generally required to disclose him to your insurance company. Failing to do so can lead to higher premiums, denied claims, or policy issues.
Three professionals engaging in a business discussion over coffee in a modern café setting.Vitaly Gariev, Pexels

Advertisement

The Smart Way to Handle It Moving Forward 

Be upfront about who drives your car. It may increase your premium—but it protects you from much bigger financial risks later.
Man holding smartphone and speaking indoors, sitting on sofa by window lighting.KATRIN BOLOVTSOVA, Pexels

Advertisement

The Bottom Line for Shared Cars 

Letting someone borrow your car isn’t always “casual” in the eyes of insurance. If it becomes routine, it becomes part of your risk profile.
A man in sunglasses stands by an open car door, viewed from the interior.Oleksandr Chepys, Pexels

Advertisement

One Last Thought Before You Hand Over the Keys 

Next time you toss your son the keys, you might ask yourself—is this just a favor… or something my insurance company already expects me to report? Because that difference can cost you. 
Happy man holding car keys while seated inside a modern vehicle.Vitaly Gariev, Pexels

Advertisement

You May Also Like:

My mechanic warned me about buying a truck with cylinder deactivation. The salesperson says it saves tons of fuel. What should I do?

My friend says electric cars are cheaper to own in the long run. My neighbor says the repairs will ruin me. Who should I believe?

Sources: 1, 2, 3


READ MORE

Rss Thumb - Hybrid Car Battery

My hybrid sat unused for months, and now the battery is weak. Are electrified cars bad for occasional drivers?

My hybrid sat unused for months and now the battery is weak. Learn why hybrids lose charge while parked, which battery may be responsible, and how occasional drivers can prevent problems.
September 4, 2026 Jack Hawkins
AI-generated image of a man standing next to a blue pickup with the tailgate down

My pickup tows plenty, but the bed is too high to load comfortably. Are new trucks becoming less useful for normal owners?

Modern pickup trucks can tow massive loads, but taller beds, off-road suspensions, and complicated tailgates may make everyday hauling harder. Here’s why truck practicality is changing for normal owners today.
September 4, 2026 Miles Rook
Fb (1)

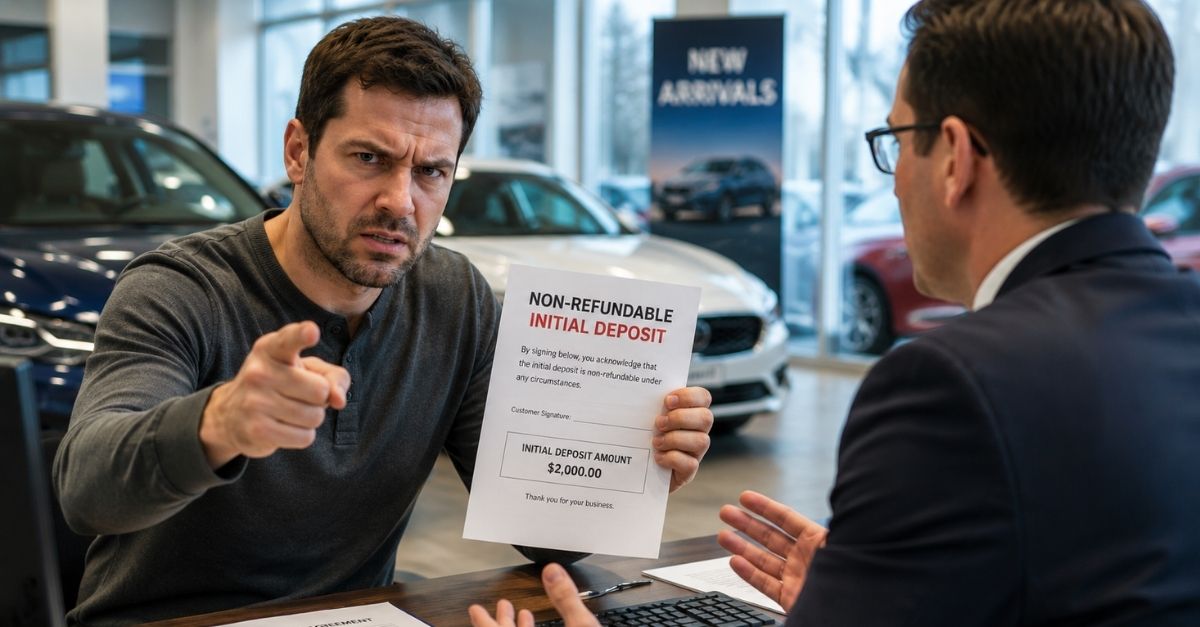
My dealership says a refundable deposit became non-refundable once the car arrived. Can they change the terms after taking my money?

A lot of car-buying trouble begins with one small payment and one big assumption. A shopper is told a deposit is refundable, the car finally arrives, and suddenly the dealer says the rules changed. That is the moment many buyers wonder whether a dealership can rewrite the deal after taking their money.
September 4, 2026 Miles Brucker
Confused Driver Inspecting Damaged Car

My insurer wants to use recycled parts to repair my nearly new car after an accident. Can I demand new parts instead?

It feels wrong at first glance. Your almost-new car gets hit, and now the insurer wants to repair it with recycled parts pulled from another vehicle. The short answer is that in many cases, you usually cannot simply demand brand-new parts, but the real answer depends on your state, your policy, and the kind of part involved.
September 4, 2026 Miles Brucker
Man at a mechanic shop

My automaker says diagnostic data belongs to them, but my mechanic says he needs it. Who controls the car’s information?

Your automaker says diagnostic data belongs to them, but your mechanic needs it to repair your car. Who really controls your vehicle's information?
September 4, 2026 Allison Robertson