The Premium Shock Is Real
If your insurer says adding your teenage son could nearly double your premium, that's not crazy. It's simply a painful reality of car ownership. Insurers usually rate every licensed driver in the household, even if one of them barely drives. The key issue is not how often he is behind the wheel. It is the risk insurers attach to newly licensed teens.
 Anastasia Shuraeva, Pexels, Modified
Why Insurers Care About Household Drivers
Auto insurers generally want every licensed driver in the home listed on the policy. The reason is simple. If your son lives with you and can get to the keys, the insurer assumes there is a real chance he could drive the car and end up in a claim.
Barely Driving Does Not Mean Low Risk
This is the part many parents hate. A teen who drives once a week can still cause a big premium jump because insurers are pricing the chance of a serious claim, not just the number of miles driven. In plain terms, a low-mileage driver can still be a very expensive risk.
Teen Drivers Have Crash Rates That Get Attention
The Insurance Institute for Highway Safety has long found that teenagers have much higher crash rates than older drivers. The group says that per mile driven, teens are more likely to be in crashes than drivers age 20 and older. That risk is a big reason insurers react so strongly when a newly licensed teen joins the household.
The Deadliest Stretch Starts Early
The Centers for Disease Control and Prevention says motor vehicle crashes are a leading cause of death for U.S. teens. The agency also reports that drivers ages 16 to 19 face a much higher crash risk than older drivers. Insurers pay close attention when the safety data keeps telling the same story.
Why Teenage Boys Often Cost More
Age and sex still affect pricing in many states because claims data shows different risk patterns by group. Young male drivers have historically been linked to more risky behavior and more severe crashes, especially in the first years after getting a license. That is why a teenage son may lead to a higher quote than a teenage daughter, depending on your state and your insurer's rules.
State Rules Can Change The Outcome
Not every state lets insurers use the same rating factors in the same way. Some states limit or ban the use of gender in pricing, and insurers also have to follow each state's underwriting and filing rules. So the exact increase can vary a lot depending on where you live.
Insurers Usually Rate The Highest Risk Driver
Many households have one or two cars that several people can drive. In that setup, insurers often assign the highest-risk driver to the most expensive or most-used vehicle for rating, depending on the company's system. That can make the premium jump look even worse than parents expect.
Occasional Use Still Counts As Exposure
Even if your son only drives to practice or runs to the store once in a while, insurers may still classify him as an occasional driver instead of ignoring him. If he is licensed and has regular access to the car, he creates exposure. The company is charging for access to the vehicle and the risk that comes with it, not just your guess at monthly mileage.
What If He Has His Own Car
Adding a teen to the family policy is often still cheaper than buying a separate policy just for that teen. Insurers usually spread risk differently on a family policy, and teens can benefit from the parents' longer insurance history and a multi-car setup. A stand-alone policy for a newly licensed teen can be extremely expensive.
The Household Rule Catches Many Families
Consumer guidance from insurers like Progressive and GEICO makes the same basic point. Licensed household members generally need to be disclosed, even if they do not drive often. Leaving a teen off the policy can create claim trouble later if the insurer decides the household was not described accurately.
Can You Just Leave Him Off The Policy
That is a risky move. If your son is licensed, lives in your home, and drives your car, your insurer may expect him to be listed. If he crashes and the company decides he should have been disclosed, you could be dealing with denied coverage, rescission in extreme cases, or nonrenewal, depending on state law and the policy facts.
Named Driver Exclusions Are Not A Universal Fix
Some insurers in some states allow a named driver exclusion, which formally excludes a person from coverage. If that option is available, it can lower the premium because the excluded teen is not insured to drive the car. But the downside is serious. If he drives anyway and crashes, there may be no coverage.
Good Student Discounts Can Help
One of the most common ways to trim the increase is a good student discount. Many insurers offer one for full-time students who keep a qualifying GPA, often a B average or better. If your son is doing well in school, ask about it directly because the savings can be meaningful.
Driver Training Can Matter Too
Completing an approved driver education course can sometimes lower premiums. The exact discount depends on the insurer and the state, but many companies reward formal training because it may reduce risk. It will not wipe out the teen surcharge, but it can help.
Telematics Might Lower The Bill
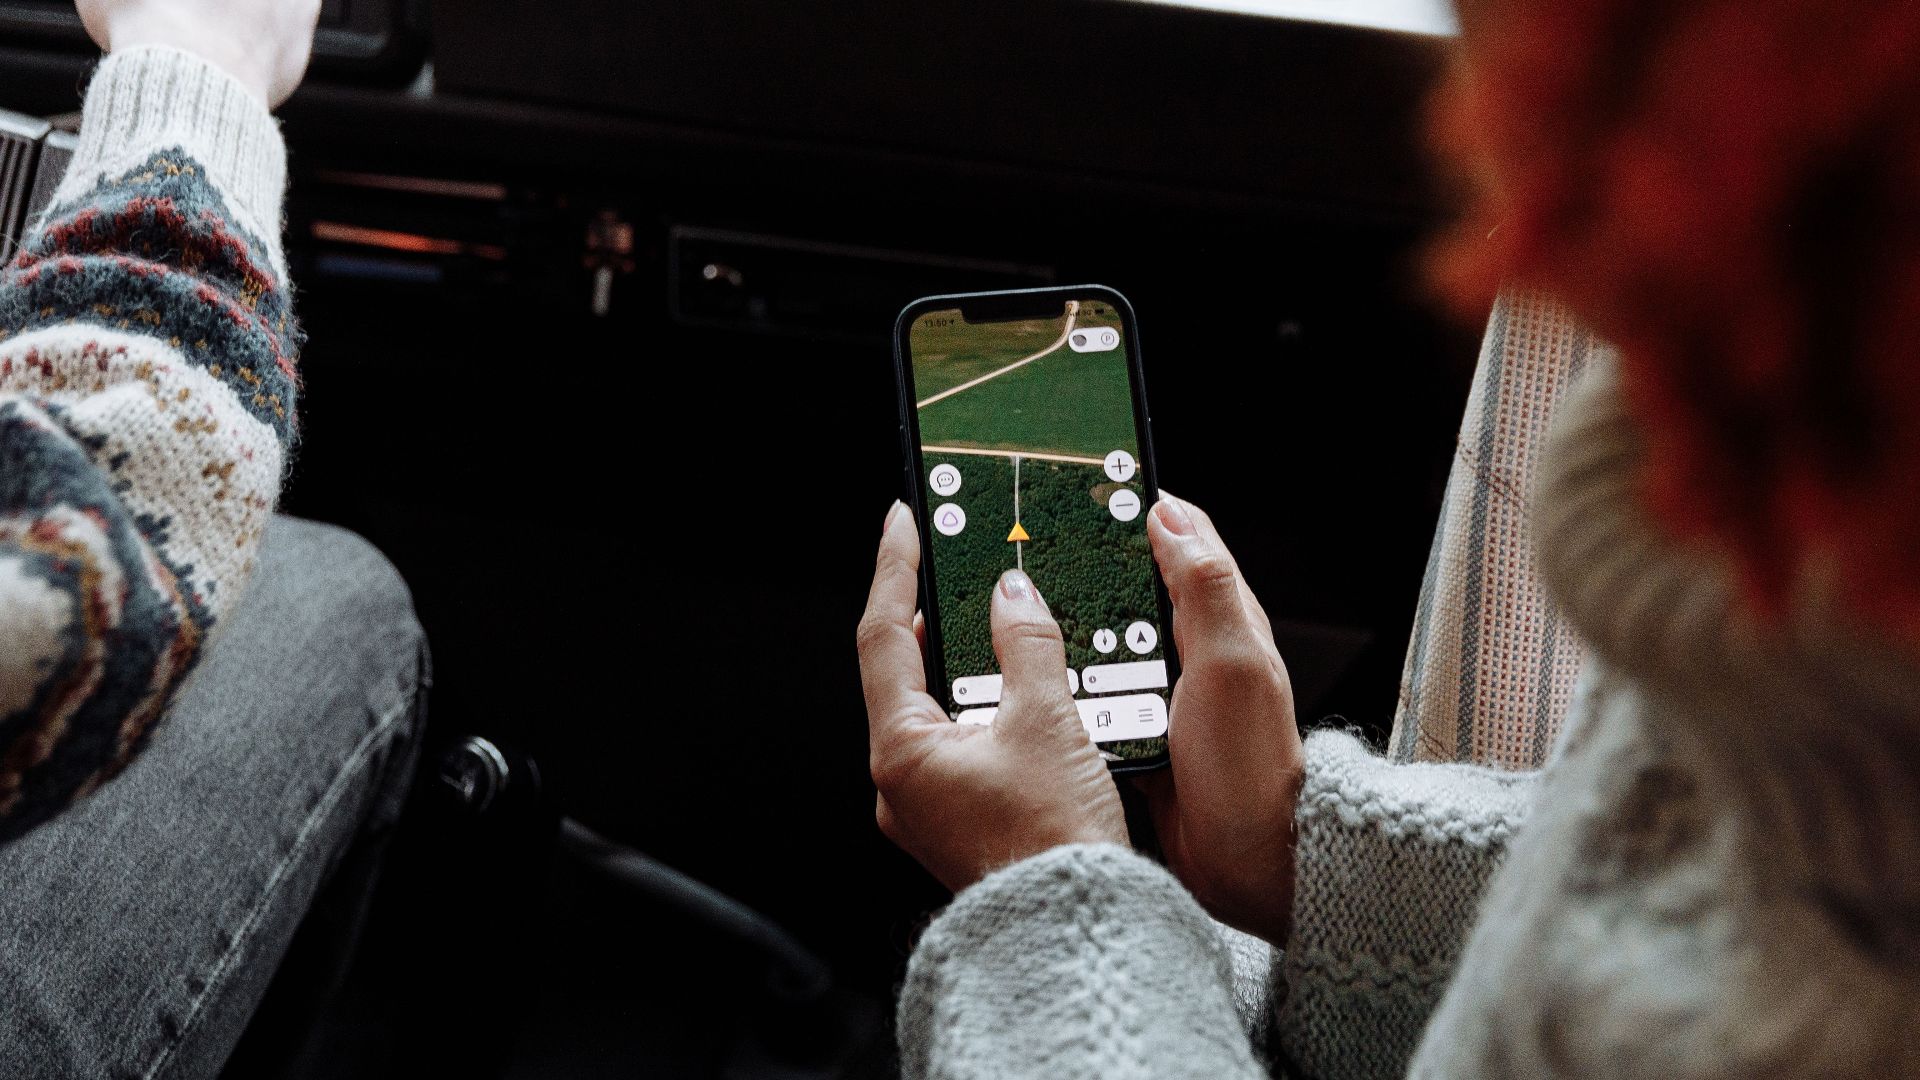
Usage-based insurance programs track driving habits through an app or plug-in device. Safe behavior like smooth braking, lower speeds, and less late-night driving may earn a discount with participating insurers. For a careful teen, this can be one of the better ways to show he is less risky than the average newly licensed driver.
The Car Choice Makes A Huge Difference
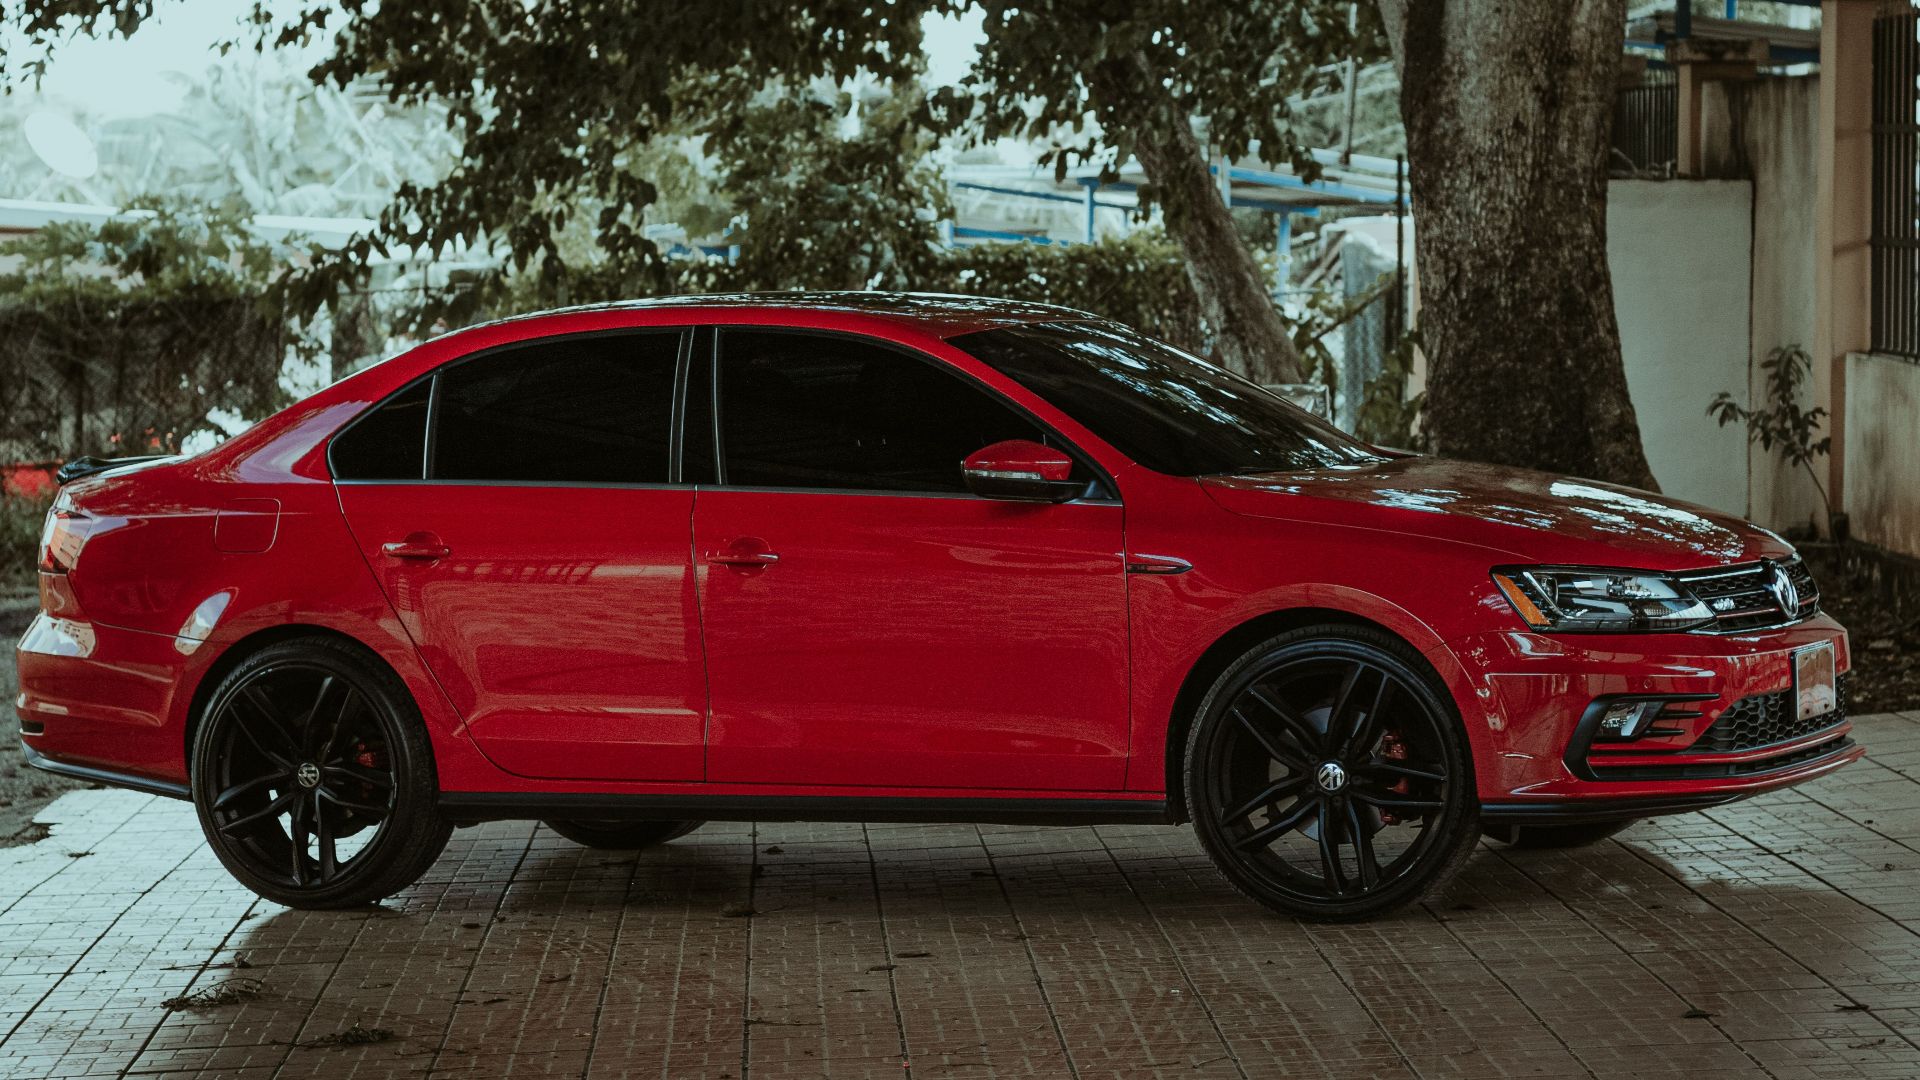
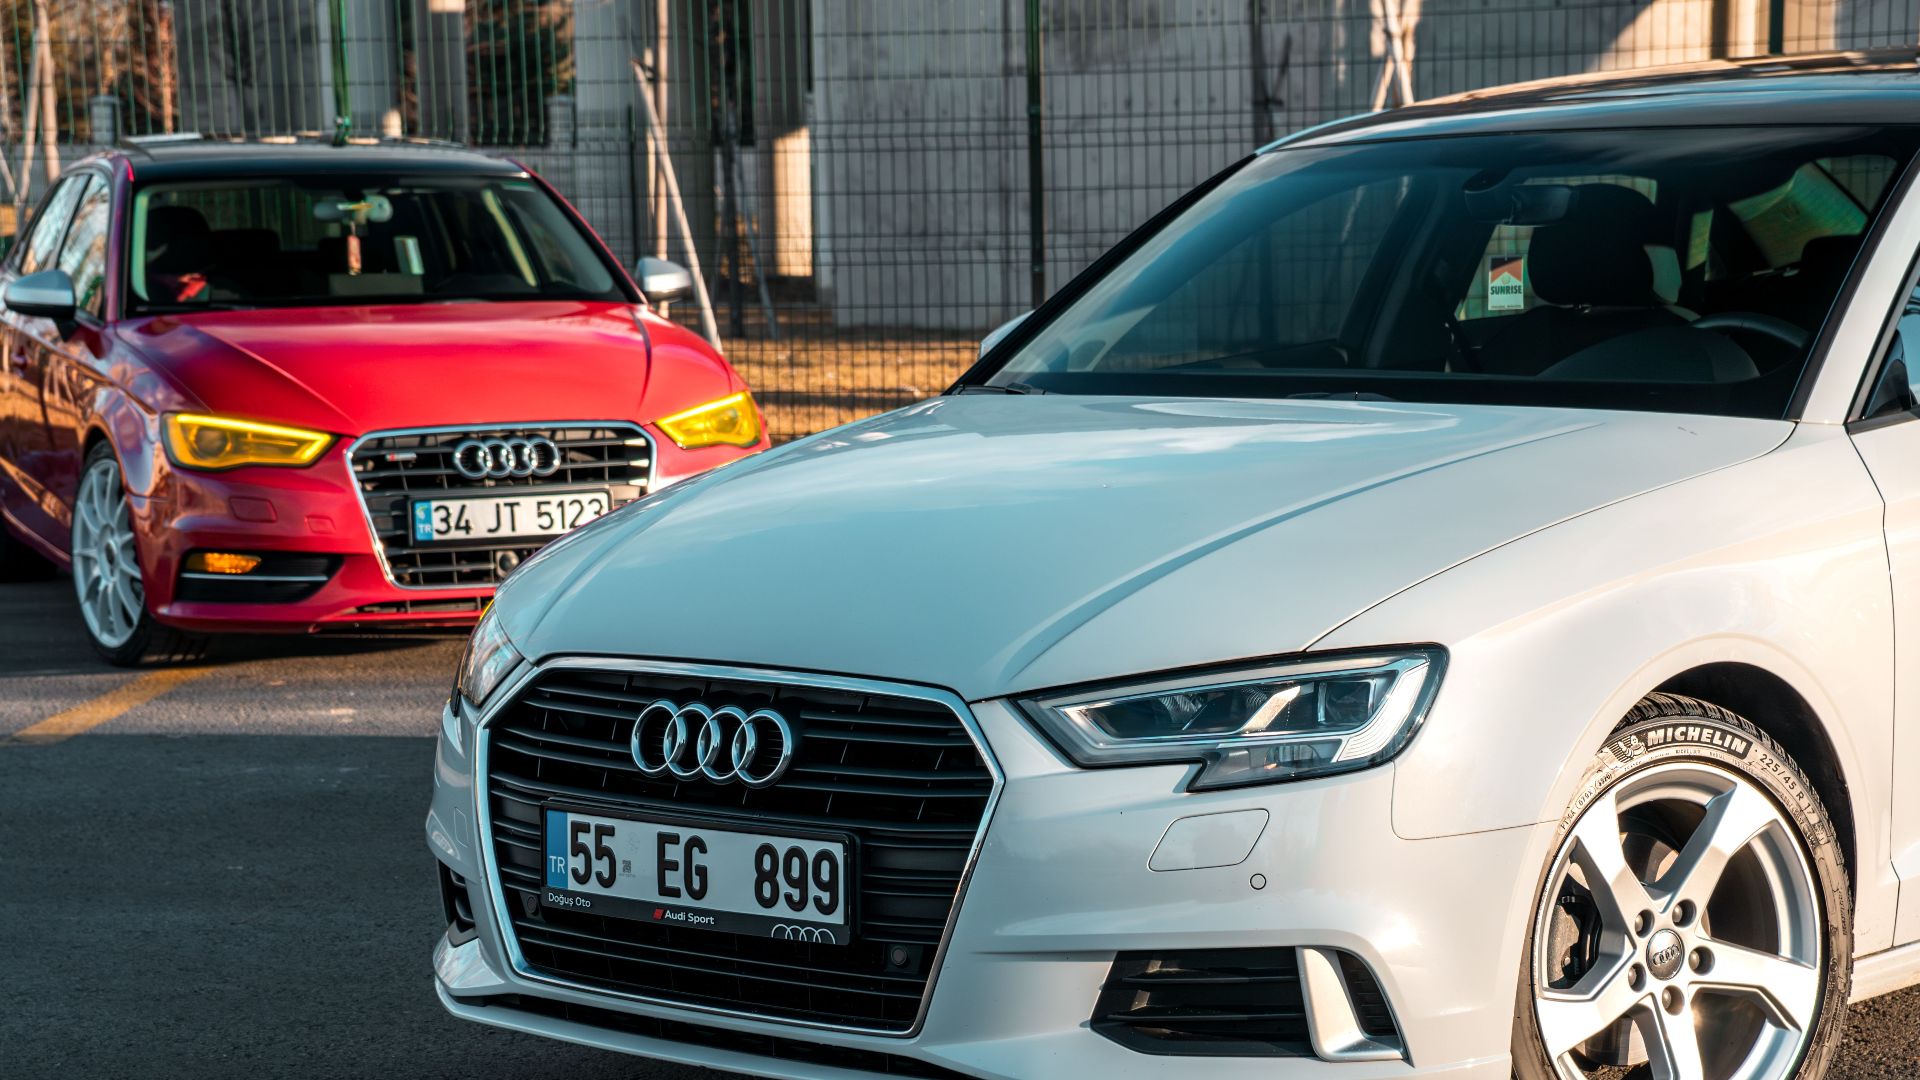
A teen assigned to a powerful or expensive car can send premiums through the roof. Choosing an older, safe, modestly priced vehicle with strong crash-test results usually helps. Insurance cost is one more reason a practical car makes more sense for a teen than something fast, flashy, or expensive to fix.
Liability Is Only Part Of The Price
Parents often focus on liability coverage, but collision and comprehensive matter too. If your teen is tied to a vehicle with high repair or replacement costs, the premium can climb fast. Modern cars packed with sensors and cameras can make even a minor crash surprisingly expensive.
Deductibles Can Shift The Math
Raising your collision or comprehensive deductible may lower the premium enough to soften the increase. This works best if you have enough savings to handle a bigger out-of-pocket cost after a claim. It is not the right move for everyone, but it is worth pricing out.
 https://kaboompics.com/, Pexels
Mileage May Matter Less Than You Think
Annual mileage can affect rates, but with a teen driver it is usually not the main factor. A newly licensed 16- or 17-year-old creates enough concern that age and inexperience often matter more. So yes, an insurer can quote a huge increase even when you point out that he barely drives.
Why The First Years Are So Expensive
The risk is highest in the first months and years after getting licensed. Data from both IIHS and the CDC shows that inexperience is a major factor in teen crashes. As your son builds driving experience and keeps a clean record, the price will often become easier to handle.
Tickets And Crashes Raise The Stakes Fast
If your son has any tickets, at-fault crashes, or distracted driving incidents, the premium impact can climb quickly. Teens already start in an expensive category, so mistakes hurt more. A clean driving record is still the biggest long-term discount there is.
Shopping Around Is Not Optional
One insurer's worst-case risk can be another insurer's acceptable one. Rating models differ, discounts differ, and some carriers are noticeably more forgiving with teen drivers. Get several quotes before accepting a big increase because the price gap can be wider than you expect.
Ask About Distant Student Status
If your son goes to school far from home and does not have regular access to the vehicle, some insurers offer a distant student discount. The details vary, and there is usually a mileage or residency requirement. Still, it is one of those less obvious questions that can save real money.
Do Not Forget Policy Structure
Bundling home and auto, keeping continuous insurance, and putting all family vehicles on the same policy can affect the final price. Those factors will not erase the teen-driver effect, but they can soften it. It is smart to ask the agent for a full discount review instead of focusing only on the teen surcharge.
When A Big Increase Is Normal
A near doubling of premium can be normal when a newly licensed teenage boy is added to a household auto policy. That does not mean you should accept every quote without question. It means the increase itself is plausible and lines up with how insurers look at household teen-driver risk.
The Best Way To Respond
Start by making sure your son is listed correctly and ask how the insurer is assigning him to vehicles. Then request quotes with every available discount, different deductible options, and possibly a different car assignment if the company allows it. Finally, compare several insurers because your best defense against sticker shock is shopping around.
The Bottom Line For Parents
Yes, it is normal for a teenager who barely drives to trigger a major premium increase. The price reflects statistical risk, household access, and the high cost of even one bad crash. The good news is that discounts, smarter car choices, and aggressive comparison shopping can often bring that number down.