That Weekend Favor Might Not Be Just A Favor
If your brother borrowed your truck for his moving business all weekend, the insurance issue is serious. Personal auto policies are usually built for everyday driving, not hauling customers’ furniture for pay. That can become a problem fast if there is a crash, an injury claim, or damage to someone’s property.
 ANTONI SHKRABA production, Pexels, Modified
Why This Can Turn Risky Fast
The main issue is commercial use. When a vehicle on a personal policy is used to make money, insurers may look hard at whether that use fits the policy or falls under an exclusion. What looks like a simple family favor can turn into a coverage fight if the truck was really being used for business.
What Insurers Mean By Commercial Use
Commercial use usually means the vehicle is being used for business. That can include hauling tools, making deliveries, transporting goods, or moving customer property for pay. If your brother was using your truck to help his moving business serve paying clients, that is exactly the kind of detail an insurer will focus on.
The Problem With A Personal Policy
The Insurance Information Institute says a personal auto policy usually covers commuting and normal personal use, but business use may call for different coverage depending on how the vehicle is used. That does not mean every work trip is excluded. It does mean the exact use, the kind of vehicle, and the policy wording all matter.
Even One Weekend Can Count
Do not assume it was harmless just because it lasted two days. Insurers usually care about what the truck was being used for at the time of the loss, not whether it was used that way all year. If it was being used for business when something happened, one weekend may be enough to create a problem.
Permission Only Gets You So Far
Most personal auto policies extend liability coverage to a permissive driver, meaning someone you gave permission to use the truck. That helps, but it is not the whole story. Coverage can still be limited or denied if the actual use falls under a business-use exclusion or some other policy restriction.
What State Farm Says About Business Use
State Farm says whether a personal policy covers business use depends on the kind of driving involved. It notes that some business driving may be covered, while some higher-risk uses may require a commercial policy. That is a good reminder that there is no one simple answer, even with major insurers.
 Manuel Camacho-Navarro, Pexels
Progressive Draws A Clear Line
Progressive says a personal auto policy may cover some business use, but it generally does not cover vehicles used mainly for business or vehicles owned by a business. It points drivers toward commercial auto insurance when the vehicle is used for work in ways that create more risk. Hauling customers’ belongings for a moving business fits that picture more than a basic drive to the office.
GEICO Spells Out The Stakes
GEICO says commercial auto insurance is meant for vehicles used for business purposes, including transporting goods and making service calls. That matters here because moving jobs involve transporting property and a higher risk of liability. Even if the truck is personally owned, the way it is being used can push things into commercial territory.
Travelers Points To Higher Liability Risk
Travelers explains that commercial auto coverage is often needed when vehicles are used for work because business driving can call for higher liability limits and more specialized protection. That can include coverage for employees, business equipment, and other job-related risks. A moving business creates exactly the kind of cargo and injury exposure insurers treat differently.
A Commute Is Not The Same As A Moving Job
Driving to work is very different from using a truck to make money on the job. Insurers often treat commuting as normal personal use, while transporting client property for a fee is more specialized and more risky. That difference is one of the biggest facts in this situation.
Liability Coverage Is Usually The First Fight
If your brother caused a crash while moving a customer, the first dispute could be over liability coverage. Injured people may sue both the driver and the owner of the truck, especially if the truck was knowingly provided for business use. If the insurer thinks the use fell outside the personal policy, it may reserve its rights or deny part of the claim.
 https://kaboompics.com/, Pexels
Damage To Your Truck Can Be Questioned Too
Even damage to your own truck may not be simple. Collision and comprehensive coverage usually follow the vehicle, but the insurer can still look into whether the loss happened during excluded or undisclosed business use. If you never told the insurer the truck might be used for moving jobs, that can make things harder.
Customer Property Is A Separate Problem
This is the part many people miss. A personal auto policy usually is not meant to cover damage to a customer’s couch, TV, or boxes in the bed of the truck. A moving business may need separate cargo or inland marine coverage for customer property, because auto insurance mainly covers vehicle-related losses, not every kind of business property claim.
Loading And Unloading Injuries Matter Too
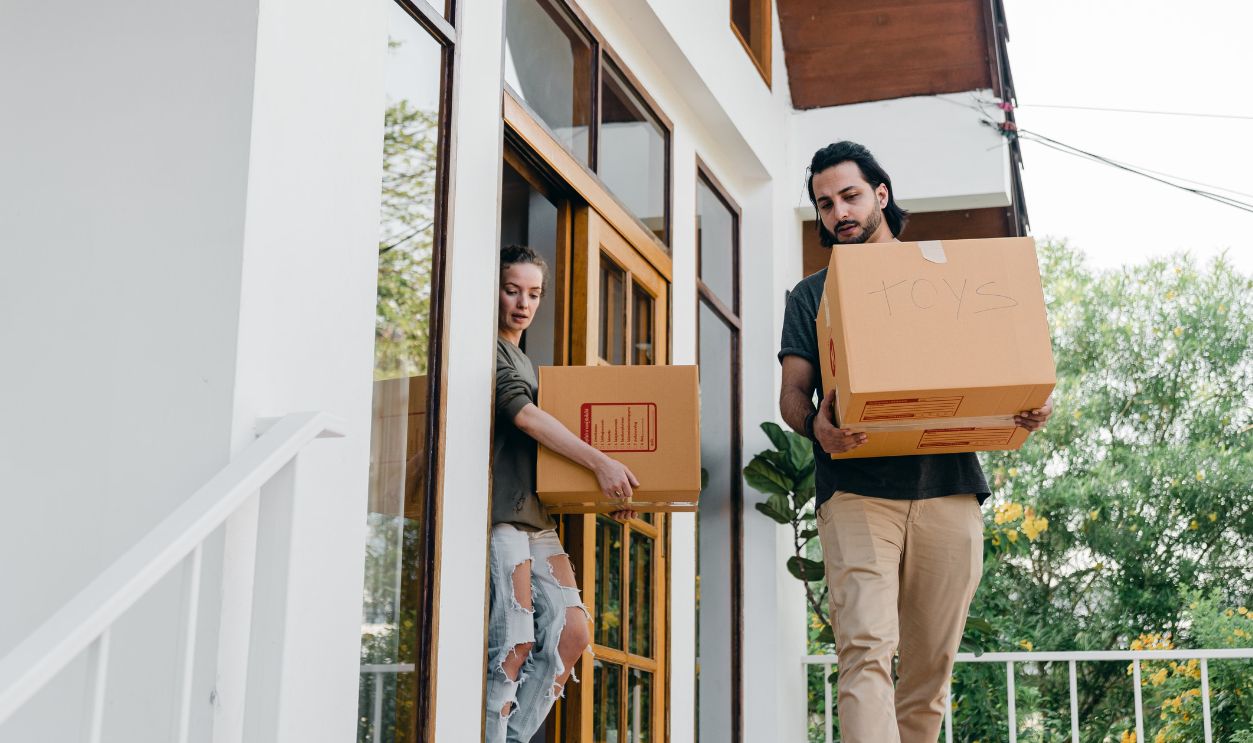
Moving work is not only about driving. People get hurt lifting dressers, walking ramps, and tying down loads, and those injuries may fall outside what a personal auto policy is meant to cover. Depending on the facts, claims could involve general liability, workers’ compensation, or other business insurance instead of your truck policy.
If He Was Paid, The Risk Gets Harder To Ignore
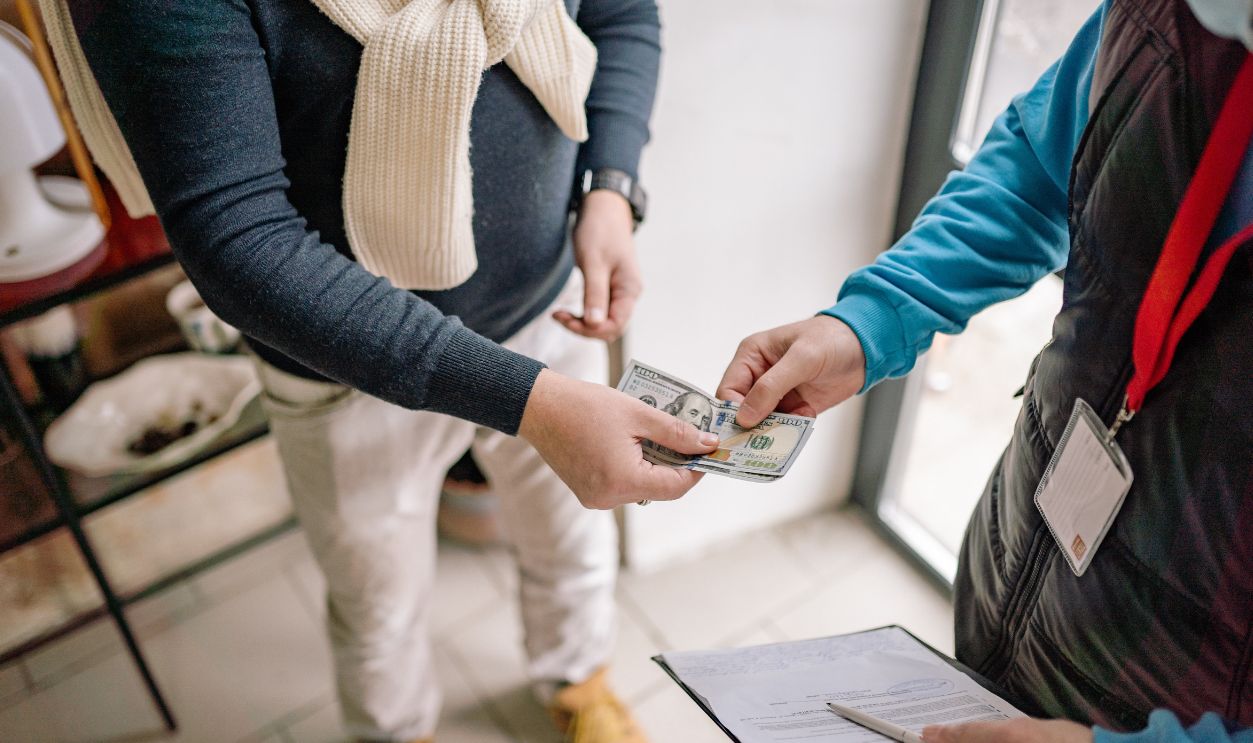
Payment changes the whole picture. Once money changes hands, the trip looks a lot less like a casual favor and a lot more like business use. That is the kind of detail claims adjusters want to know right away.
If He Helped Someone For Free, The Analysis Can Change
Not every move raises the same insurance issue. Helping a friend or relative move once, with no pay and outside any business, may look more like normal permissive use. But this situation involves a moving business, and that business connection is what raises the red flag.
 https://kaboompics.com/, Pexels
Why Insurers Ask How Often It Happens
Insurers often want to know whether the use was occasional or ongoing. A one-time errand may be treated differently from using the truck for jobs every weekend. Still, even occasional commercial use can matter if the policy excludes it or if the insurer would have priced the policy differently had it known.
Your Brother’s Insurance May Not Rescue You
Some people assume the borrower’s own insurance will fix everything. In many cases, auto liability coverage follows the vehicle first, with the driver’s coverage only stepping in as excess in some situations. That means your policy could be involved before anyone even gets to his.
The Truck Owner Can End Up In The Middle Of It
As the owner, you could be named in a lawsuit after a crash, especially if someone claims you should not have let the truck be used for commercial work. That does not mean you automatically lose. It does mean the legal and insurance mess can reach you even if you were nowhere near the move.
SBA Guidance Adds Some Context
The U.S. Small Business Administration says business owners should carefully review their insurance needs, including coverage tied to vehicles used in the business. That general guidance does not decide any single claim, but it drives home an important point. Once a vehicle becomes part of earning income, business insurance questions become very real.
What To Check In Your Policy Right Now
Look at your declarations page and the full policy booklet, not just the insurance card in the glove box. Check the sections on exclusions, business use, permissive drivers, vehicle use, and misrepresentation or failure to disclose important facts. If the wording is not clear, call the insurer or agent and ask for an answer in writing.
Questions To Ask Your Agent
Ask whether your truck is covered if a relative uses it for a paid moving job. Ask whether customer property, loading injuries, and repeated weekend business use are covered or excluded. Also ask whether the insurer offers an endorsement or whether a commercial auto policy is needed for that kind of work.
Do Not Wait For A Crash
The worst time to find a coverage gap is after a claim is filed. At that point, every text, invoice, and social media post about the move can become proof of commercial use. Sorting it out ahead of time is cheaper, easier, and far less stressful.
If Nothing Happened This Time, It Still Matters
If the weekend is already over and there was no accident, you still learned something useful. Your truck may be one borrowed favor away from being used in a way your insurer never meant to cover. That is a good reason to set rules now and update coverage before the next request comes in.
The Bottom Line
Yes, commercial use could cause insurance problems if your brother used your truck for his moving business all weekend. The exact outcome depends on your policy wording, the insurer’s rules, the details of the jobs, and whether money was involved. But in practical terms, using a personally insured truck to move customers’ property for pay is the kind of situation that often calls for commercial coverage, not guesswork.
The Next Step
Call your insurer or agent, explain exactly what happened, and ask for a clear answer in writing. If your brother plans to do this again, he should look into commercial auto coverage and any separate insurance needed for customer property and business liability. That is the step most likely to protect your truck, your money, and your family relationships.